Latest
When you need urgent funds, whether for a home renovation, a medical emergency, or consolidating high-interest credit card debt, your first instinct might be to visit your bank’s website or local branch. However, the borrowing landscape in India has evolved rapidly. Today, digital-first personal loan marketplaces offer a modern, highly efficient alternative to traditional banks.
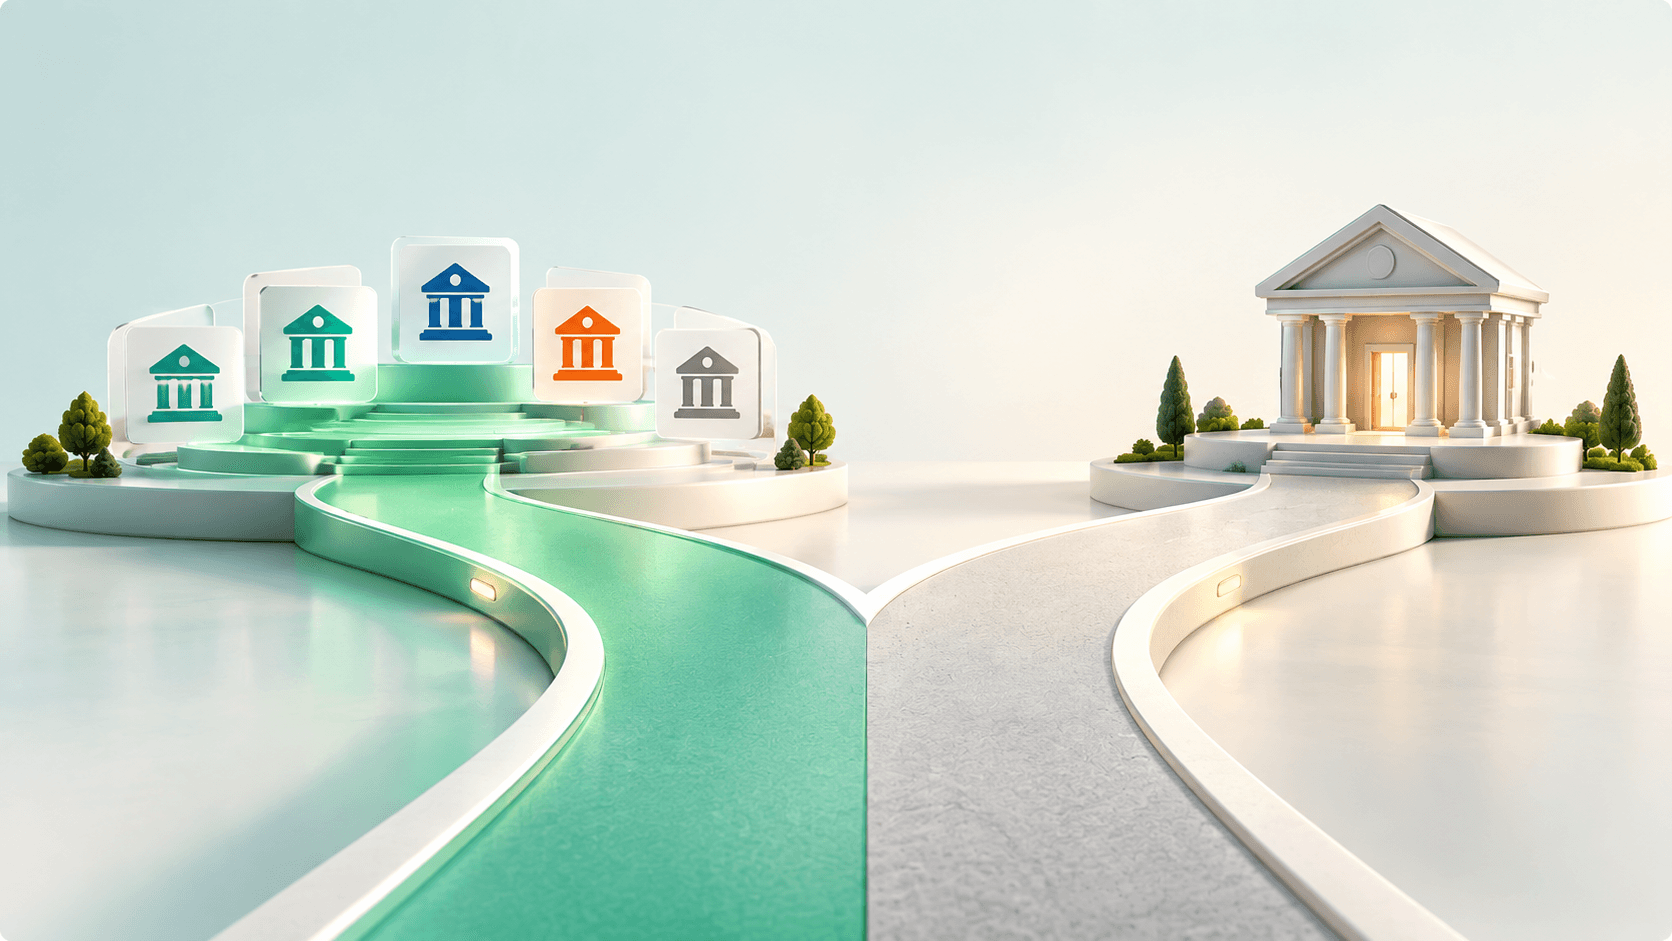
If you are planning to apply for a personal loan online, you face a critical choice: Should you apply to a single bank directly, or should you use a personal loan marketplace like Bridge Capital?
To make an informed financial decision, you must understand how both options impact your interest rates, application effort, and credit health. Let’s do a comprehensive deep dive.
The Traditional Route: What is a Direct Bank Loan?

A direct loan involves applying directly to a specific financial institution, either a traditional public/private bank (like HDFC, ICICI, or SBI) or a non-banking financial company (NBFC).
For decades, this was the only way to borrow. You walked into a branch, spoke with a manager, submitted physical stacks of paperwork, and waited days for approval. While most banks now offer digital portals, the underlying mechanism remains the same: you are dealing with a single institution.
The Pros of Direct Bank Loans
- Pre-approved Offers: If you have held a salary or savings account with a bank for years, they may offer pre-approved, "instant" personal loans.
- Familiarity: Some borrowers feel more comfortable dealing with a bank where they already have an active relationship.
The Cons of Direct Bank Loans
- The "Take It or Leave It" Trap: You only see one offer. You have no way of knowing if another reputable bank would have offered you a 2% lower interest rate or waived the processing fee.
- Strict, Unyielding Eligibility: Every bank has highly rigid criteria. If your income, location, or credit score misses their threshold by a fraction, your application is rejected instantly.
- Heavy Credit Score Damage: If you are rejected and try to apply to another bank, and then another, each bank makes a separate "hard inquiry" on your credit profile. Multiple hard inquiries in a short span can severely drop your CIBIL score.
The Modern Alternative: What is a Personal Loan Marketplace?

Think of a personal loan marketplace as the "MakeMyTrip" or "Amazon" of personal finance. Instead of booking a flight on a single airline's website, you use a platform to compare all available flights, prices, and times side-by-side.
A digital marketplace (like Bridge Capital) acts as your financial navigator. You fill out a single, 100% digital application. The marketplace’s advanced algorithms then analyze your financial profile and instantly match you with tailored loan offers from a massive network of 100+ trusted, RBI-regulated banks and NBFC partners.
Detailed Comparison: 5 Critical Factors to Consider
To truly understand why millions of Indians are switching to marketplaces, let’s compare them across the five most important pillars of borrowing:
1. Interest Rates & Processing Fees
- Direct Bank: You are locked into whatever rate that specific bank decides to offer you based on their internal risk algorithms.
- Marketplace: Multiple lenders actively compete for your business. Because you can view and compare interest rates from 100+ lenders side-by-side, you have the leverage to choose the absolute lowest rate and most affordable EMI structure.
2. CIBIL Score Protection
- Direct Bank: Every single direct application triggers a "Hard Pull" on your CIBIL report. If you apply to three banks directly to compare rates, your score will take a hit.
- Marketplace: Marketplaces use a single "Soft Pull" to fetch your credit profile and match you with lenders. A soft pull has zero impact on your credit score, allowing you to compare dozens of offers safely.
3. Application Convenience & Paperwork
- Direct Bank: If you apply to three different banks, you must fill out three separate forms, upload your KYC documents three times, and answer follow-up calls from three different sales teams.
- Marketplace: You fill out one single digital form on an app or website. Your documents are uploaded once, and the marketplace securely coordinates with the lenders behind the scenes.
4. Approval Rates
- Direct Bank: Very low flexibility. If you don't fit their exact box, you get a "No."
- Marketplace: Exceptionally high approval rates. Because marketplaces have a diverse network of lenders ranging from premium private banks to flexible NBFCs, if Bank A rejects your application, NBFC B or C might gladly approve it.
5. Operational Coverage
- Direct Bank: Many banks only serve major Tier 1 and Tier 2 cities where they have physical branches.
- Marketplace: Built on digital infrastructure. For example, Bridge Capital connects you with lenders serving over 19,000+ pin codes across India, bringing elite borrowing options to remote towns and metros alike.
Common Myths About Loan Marketplaces Debunked
Many borrowers hesitate to use marketplaces due to common misconceptions. Let's clear the air:
Myth 1: "Marketplaces charge extra fees to the borrower."
- Fact: Using a marketplace like Bridge Capital is 100% free for the borrower. Marketplaces are compensated directly by the financial institutions for helping them find qualified borrowers. You will never pay a rupee extra.
Myth 2: "Marketplaces are only for people with bad credit."
- Fact: Marketplaces cater to the entire spectrum of borrowers. Whether you have an elite CIBIL score of 800+ looking for premium rates, or a lower score looking for flexible NBFC approvals, a marketplace finds the perfect fit.
Conclusion: The Verdict
If you value your time, want to protect your credit score, and are determined to secure the absolute lowest interest rate in India, a personal loan marketplace is the superior choice.
By applying once through a platform like Bridge Capital, you gain instant leverage over 100+ lending partners across 19,000+ pin codes.
Ready to experience smarter, human-first borrowing? [Apply for a personal loan on Bridge Capital today] 100% digital, fast approval, and designed around you.
Frequently Asked Questions
Q1. Is a personal loan marketplace safe and secure?
Yes, reputable marketplaces like Bridge Capital use bank-grade encryption to protect your personal and financial data. Furthermore, they only partner with RBI-regulated banks and non-banking financial companies (NBFCs), ensuring complete safety and compliance.
Q2. Do I need to pay any charges to use Bridge Capital?
No. Bridge Capital’s platform is completely free to use for borrowers. The interest rates and processing fees you pay are charged directly by the lending bank or NBFC that issues your loan, with no hidden markups.
Q3. Will checking my offers on a marketplace reduce my CIBIL score?
No, checking your eligible loan offers on a marketplace initiates a "soft credit inquiry" which has absolutely no impact on your CIBIL score. A hard inquiry is only generated once you formally choose a specific lender and proceed with final disbursal.
Q4. How does a marketplace find the lowest interest rate for me?
Because a marketplace connects you to a network of 100+ lenders, it automatically filters and displays loan offers ranked from lowest interest rate to highest. This allows you to choose the absolute cheapest option in seconds.
Q5. What happens if a direct bank rejects my loan application?
If a direct bank rejects you, you must find another bank, re-apply, and submit your paperwork again, resulting in another hard CIBIL pull. On a marketplace, if one partner rejects you, the system automatically redirects your profile to other matching partners instantly, ensuring zero wasted time.